Mobile app development for London businesses
London’s fintech sector includes Revolut and Monzo, so a new finance app here is compared with theirs from the first screen.
More
We build iOS and Android apps from €4,750 for fintechs, study teams and event exhibitors, with one codebase and the security review planned in.
Three apps that make sense in London
Situations where a phone app does a job a website cannot.
- 01A fintech’s customer app
The product works, but the app was rushed out for a beta: sessions drop, card controls open in a web view and support covers the gaps.[1]
An app with biometric login, instant card controls and in-app statements, built so that a security review finds a clear record of every action.
- 02A clinical study’s participant app
A life sciences team hands volunteers paper diaries to take home and chases missing entries by phone.[1]
Participants log symptoms in an app that reminds them at the right moment, consent is stored by version, and the team sees gaps the same day.
- 03An exhibitor at ExCeL London
Stand staff collect leads on paper forms and business cards, then type them into the CRM a week after the show.[2]
An app takes a quick note per visitor, tags each lead by interest and sends it to the CRM before the visitor has left the Royal Docks.
Projects we can show you
 Mobile · RetailMobile App for a Beverage ChainBuilt from scratch: loyalty, gamification, sales analytics.
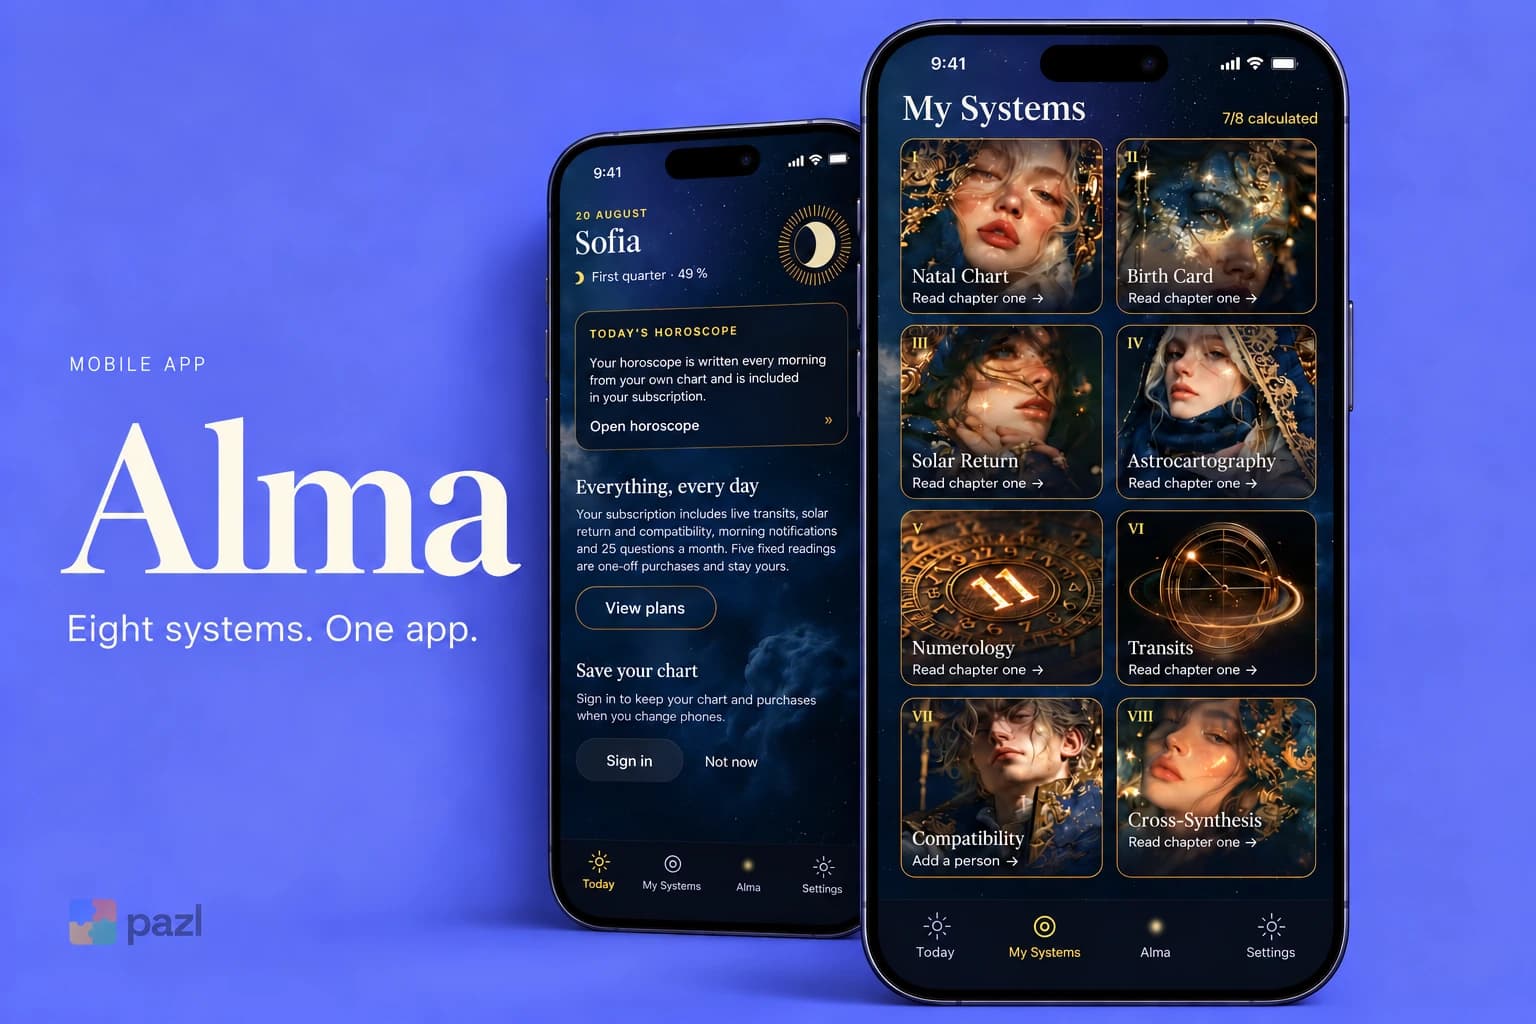 Mobile · Own productAlma: Natal Chart AppiOS and Android: eight systems, a reading and chat.
 ConceptMobile · CoffeeCoffee Shop App: Order AheadFavourites, drink options, pickup time, one-tap reorder.
Payments on a UK phone, and who reviews app data
Tapping a card or phone is how much of the UK pays, Direct Debit carries the regular bills and 22% of adults used buy now pay later in 2025.
- Debit cards
- Contactless
- Faster Payments
- Direct Debit
- Buy Now Pay Later
- Open banking
More
Any app that holds personal data answers to the Information Commission.
- Debit cardsThe most used method in 2025, with 26.6 billion payments; cards made up 64% of all UK payments.[3]
- Contactless19.2 billion contactless card payments in 2025, while cash fell to 8% of all payments.[3]
- Faster PaymentsWith other remote banking, 6.2 billion payments in 2025: the second most used method after debit cards.[3]
- Direct DebitGrew 2% to 5 billion payments in 2025, 10% of all UK payments.[3]
- Buy Now Pay Later12.9 million UK adults, or 22%, used it at least once in 2025.[3]
- Open bankingPassed 1 billion payments and 100 billion API calls in September 2026.[4]
What the price covers
The same offer, price and scope as on our main page for this service.
- Agreed screens in your brand
- iOS and Android, one codebase
- Backend and admin, as needed
- Stripe, Apple, Google Pay where relevant
- Help submitting to both stores
- 6-month warranty, full IP transfer
One app for iPhone and Android, or two?
One codebase covers both for most products, fintech and study apps included, which keeps a first release within reach; apps start from €4,750. Heavy graphics or unusual hardware access can justify native code, and we say so before quoting.
Can a fintech app pass a bank partner’s security review?
We design for it: biometric login, encrypted storage on the device, short sessions, certificate pinning where the partner asks for it, and a written record of each data flow. The review then works from documents instead of guesses.
Who publishes the app in the stores?
You do, under your own developer accounts, with us preparing the listings, screenshots and the privacy answers Apple and Google ask for. A study app also needs its data use described screen by screen, which we write with your data protection officer.
Which payment options should the app offer?
Cards and wallets first, since UK contactless card payments reached 19.2 billion in 2025. Regular charges suit Direct Debit, which grew to 5 billion payments, and open banking lets customers pay from their bank app without typing card details.
20-second estimate.
Pick scope and add-ons.
A project in London?
Tell us what you need and by when. We reply with questions or a first estimate.
Plenty of London firms have deep expertise wrapped in a thin layer of software: a fintech with a careful risk model and a manual back office, a study team with a strong protocol and paper diaries.
More
From our blog
Checked on 14 November 2026
All 5 sources
- business.gov.uk/invest-in-uk/investment/regions/london-england
- excel.london/about-us
- ukfinance.org.uk/system/files/2026-08/PaymentMarketsReport_2026…
- openbanking.org.uk
- gov.uk/government/organisations/information-commissioner-s-offi…
The facts about the city and its country come from the pages listed, read on that day. Rules change: confirm what applies to your company with your tax adviser.