Online payments in the UK: Open Banking, cards and Direct Debit
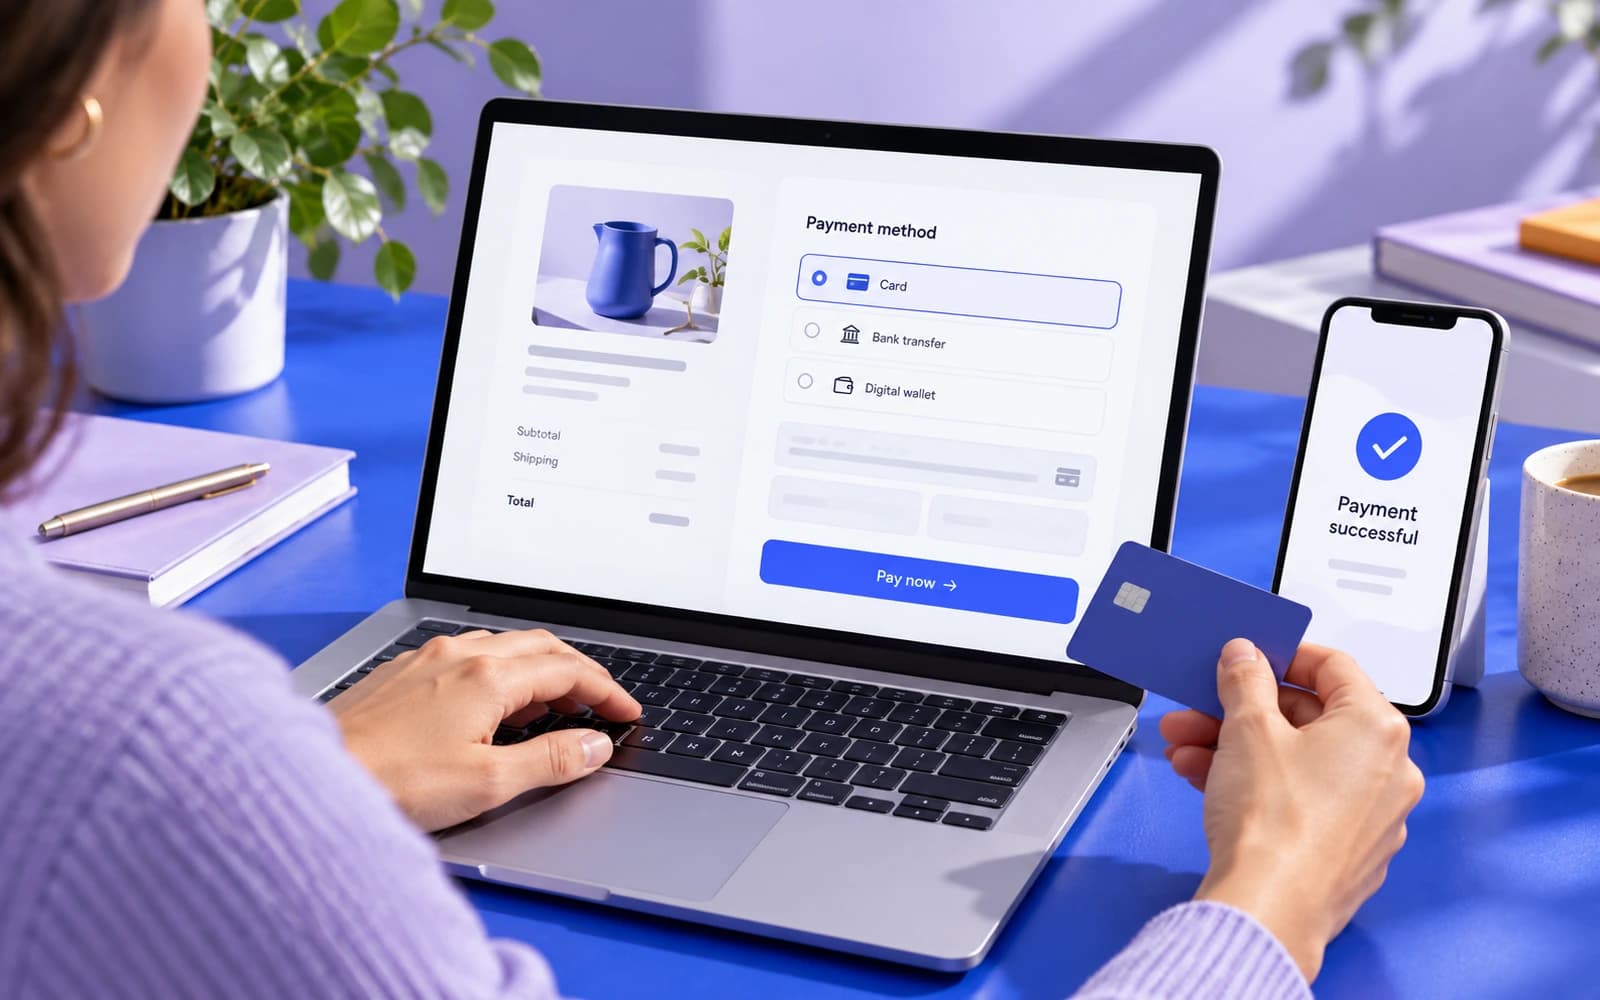
A UK website or app should take cards with strong customer authentication and can add pay by bank, a payment service regulated under the Payment Services Regulations, and recurring payments.
More
This guide covers the rules behind a UK checkout and what we build into it.
 Clinic Website with Online BookingSources checked on 12 November 2026
What applies in the UK
The rules and schemes behind a UK checkout.
- In forceOpen Banking
- In forceRecurring payments
- In forceCard authentication
- Checked on 12 November 2026
More
- In force
- In forcePay by bank
Starting a payment from a customer’s bank account (payment initiation) is a regulated payment service under the Payment Services Regulations 2017.[3]
- In force
- In force
- Checked on 12 November 2026
Sites that book, sell, explain.
Related pages
More
Online store prices, chatbots that take payments and e-invoicing.
- Online store
- Custom stores, B2C and B2B.
- Chatbot
- WhatsApp, Telegram and website chat.
- E-invoicing and MTD in the UK
- Making Tax Digital today, e-invoices from 2029.
What we build into a UK checkout
Through your payment provider; card data never touches your server.
- Cards and wallets
- Pay by bank
- Subscriptions and invoices
More
- Cards and wallets
- Card, Apple Pay and Google Pay through a hosted checkout, which handles strong customer authentication.
- Pay by bank
- Open Banking payments through an FCA-authorised provider, useful for larger invoices and deposits.
- Subscriptions and invoices
- Direct Debit or card subscriptions, with payments matched to orders in Xero or QuickBooks.
Questions before we build the checkout
Answer these and the payment part of your quote is clear.
Tick the ones that apply to you.
More
- Methods
- Which payment methods do your customers use today?
- Provider
- Do you already have a provider, and does it offer pay by bank?
- Recurring
- Are there subscriptions, instalments or deposits?
- Refunds
- Who issues refunds, and from which screen?
- Accounting
- Should every payment reach your accounting automatically?
Read more on this
Checked on 12 November 2026
A summary for planning software, not legal or tax advice. Rules change: check the source or ask your adviser before you rely on a date.
Sources
- CMA: Retail Banking Market Investigation Order 2017
- Open Banking Limited: Glossary
- legislation.gov.uk: The Payment Services Regulations 2017, Schedule 1
- Open Banking Limited: Variable Recurring Payments required for sweeping
- FCA: Open banking, launch of the UK Payments Initiative scheme
- Pay.UK: Faster Payment System
- Bank of England: Payment and settlement
- FCA: Deadline extension for Strong Customer Authentication
- HM Treasury: Modernising payment services regulation
Questions we get asked
Do I need to be FCA-authorised to take Open Banking payments?
Usually not: an authorised payment initiation provider does it for you. Check the exact setup with your provider.
Which provider do you use?
Yours, or Stripe if you have none. We integrate the provider; the account and the money stay with you.
What does a website with online payments cost?
Websites start from €2,500. Payments are part of the scope and priced in the quote.
Local rules belong in the first scope, not in a fix after launch. That is why we put them into the quote.
Add payments to your site or app
Tell us your provider and methods; we price the integration.